Emergency Gutter Repair
Does Homeowners Insurance Cover Gutter Damage in NH?
Homeowners insurance often pays for gutter damage from a sudden covered event, such as wind or a falling tree, and usually does not pay for wear, rust or neglect. Policies differ, and your insurer decides what is covered. Read your own policy, photograph the damage before you clear it and ask your agent before you hire out repairs.
- ★ 5.0 on Google · 29 reviews
- Serving since 2024
- Based in Hampstead, NH
Published and updated November 2, 2026 · By the Lanes Gutters crew, Hampstead, NH
On this page
Home insurance and gutters is a question with a general pattern and a lot of exceptions. This guide explains the pattern, not your policy. We install and repair gutters, we are not your insurer, and we cannot tell you what yours covers. For the repair itself, see our storm-damaged gutter repair page, which sits in emergency gutter repair.
Does homeowners insurance cover gutters?
Often, when the damage is sudden and the cause is covered. Rarely, when the damage is slow. Gutters are normally treated as part of the house, but whether a particular loss is paid depends on the policy's wording, its exclusions and your deductible.
| Situation | General pattern |
|---|---|
| Wind tears a gutter off | Often covered as sudden damage |
| A tree limb falls on the gutter | Often covered as a covered event |
| Ice or snow weight bends or pulls a run | Often considered, but policies differ |
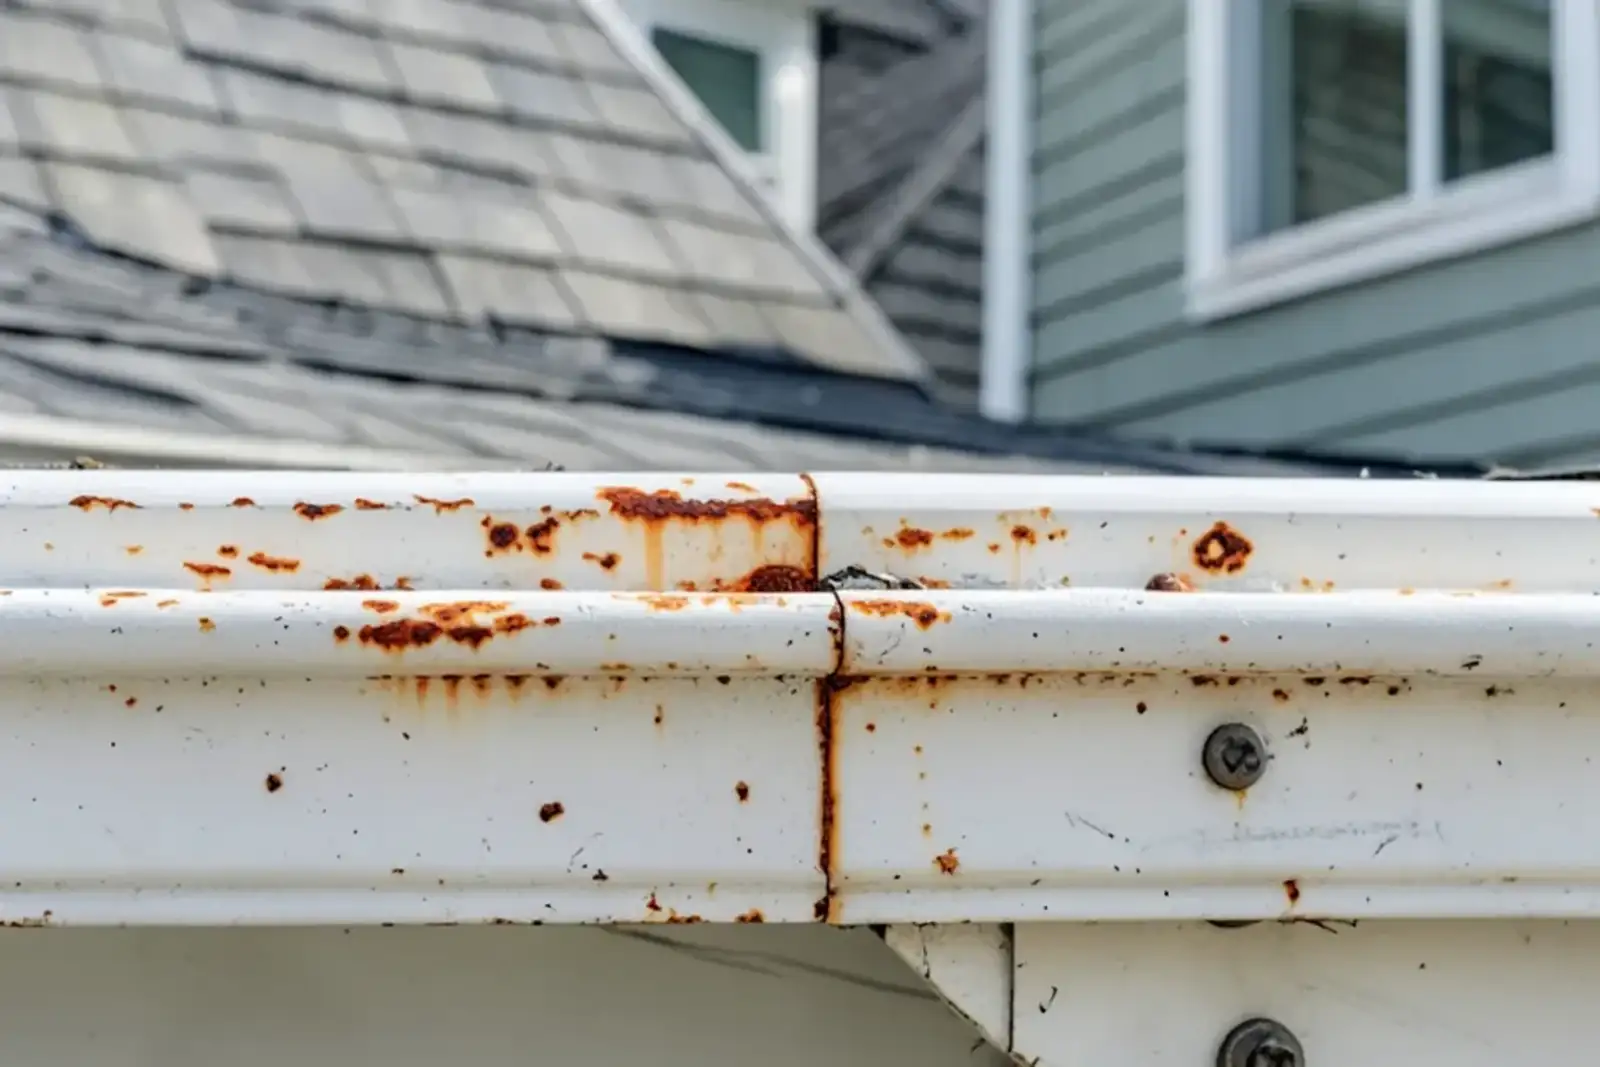
| Rust, old sealant, sagging from age | Usually treated as wear and not covered |
| Clogs, overflow, neglected upkeep | Usually treated as maintenance |
| Flooding at the ground | Usually needs a separate flood policy |
This table describes patterns, not rules. Your insurer decides.
Sudden event or slow wear
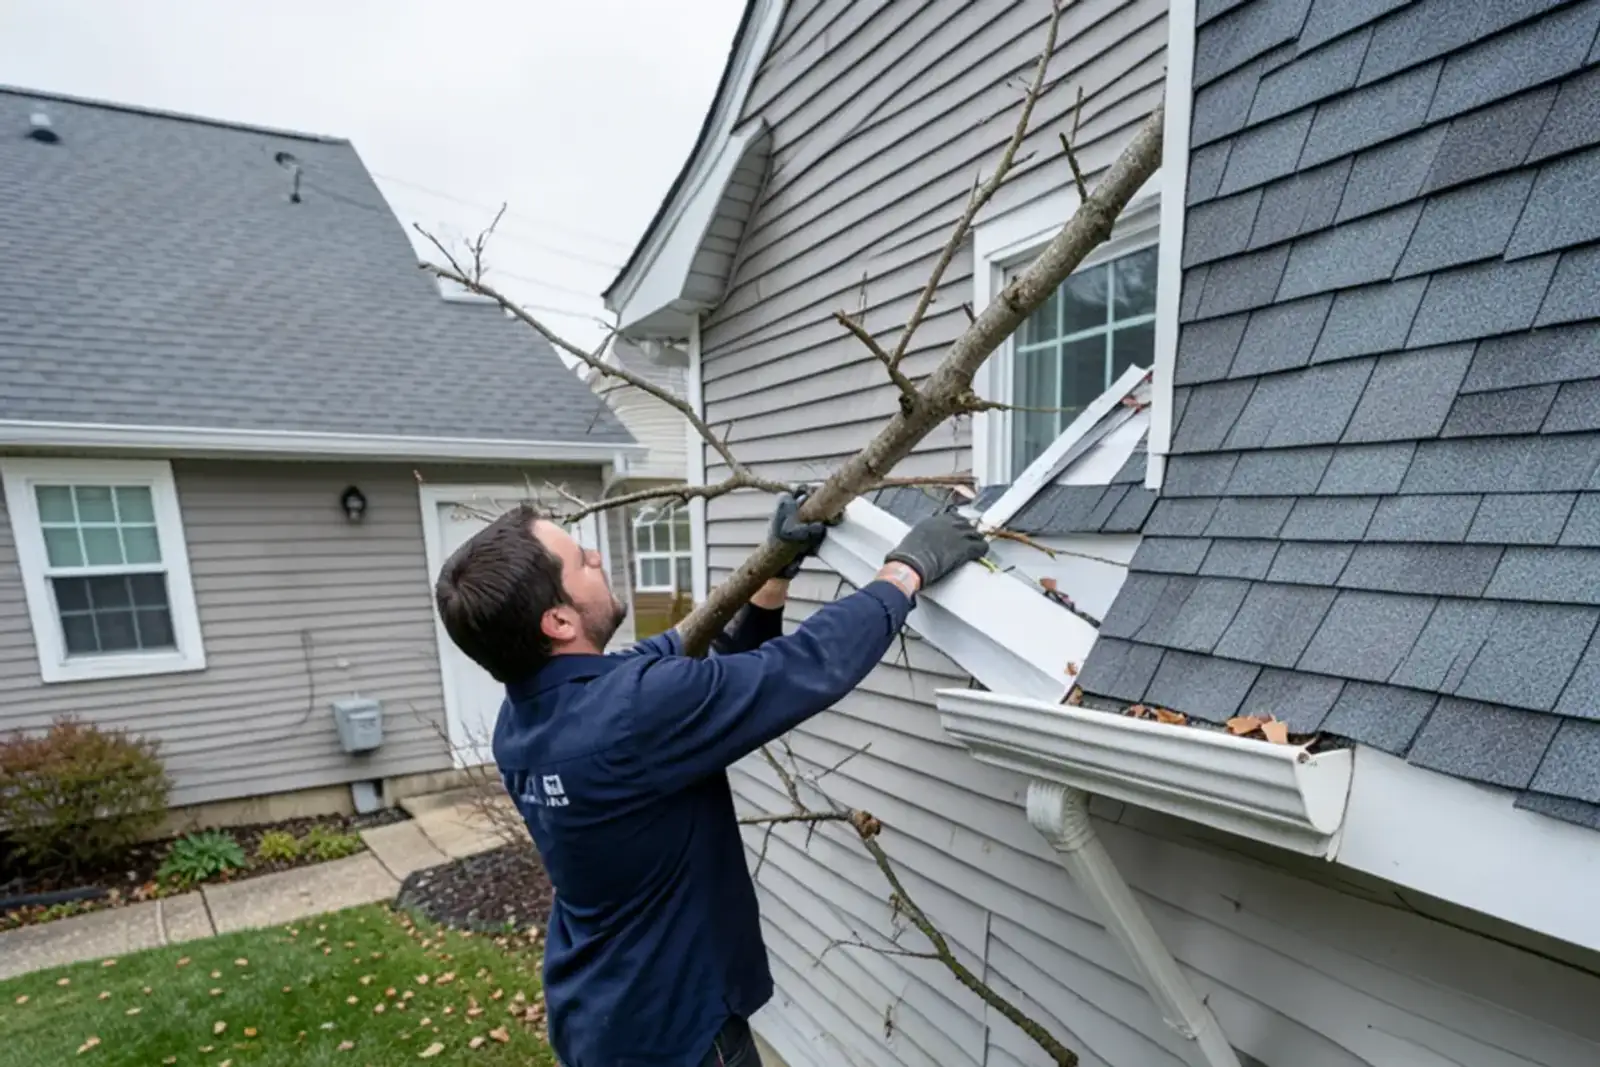
The distinction that matters most is how the damage happened. Insurers generally pay for sudden and accidental loss from a named cause. They generally do not pay to replace something that wore out, rusted or was never maintained.
A gutter ripped off in a windstorm is a sudden event. A gutter that sagged for ten years, leaked at every seam and rotted the fascia is wear. The two can look alike on the ground, which is why photos and the age of the gutter come up.
The deductible question
A claim has to clear your deductible before it pays anything. A repair to a section of gutter may cost less than the deductible, and then a claim does nothing but add paperwork to your file. Ask your agent how a claim is recorded before you file, and compare the written repair price with your deductible.
Larger losses change the math. A run torn off along with fascia, soffit or siding is a bigger number, and a claim may make sense.
Replacement cost, depreciation and matching
Two policy terms change what a claim pays. Replacement cost coverage pays to put back the same thing new, usually less the deductible. Actual cash value coverage subtracts depreciation for age first, which on a gutter that is 25 years old can shrink the check a lot. The policy declarations page says which one you have.
Matching is the other. If one side of a house is damaged and the rest is sound, policies and insurers handle the question of matching the new section to the old in different ways. Some also carry a separate, often higher, deductible for wind or hail. These are questions for your agent, not for us, and the answers sit in your own policy.
What a claim usually needs
Steps differ by insurer, but the same items come up again and again:
- Make the home safe. Prevent further damage with reasonable temporary steps and keep receipts.
- Photograph everything before you clear it. Wide shots and close shots, with dates.
- Read the policy. Look at covered causes, exclusions and your deductible.
- Report the loss. Call your insurer or agent and ask what they require and how fast.
- Get a written price. Itemized by gutter, hangers, downspouts and wood work.
- Keep the old parts if asked. An adjuster may want to see them.
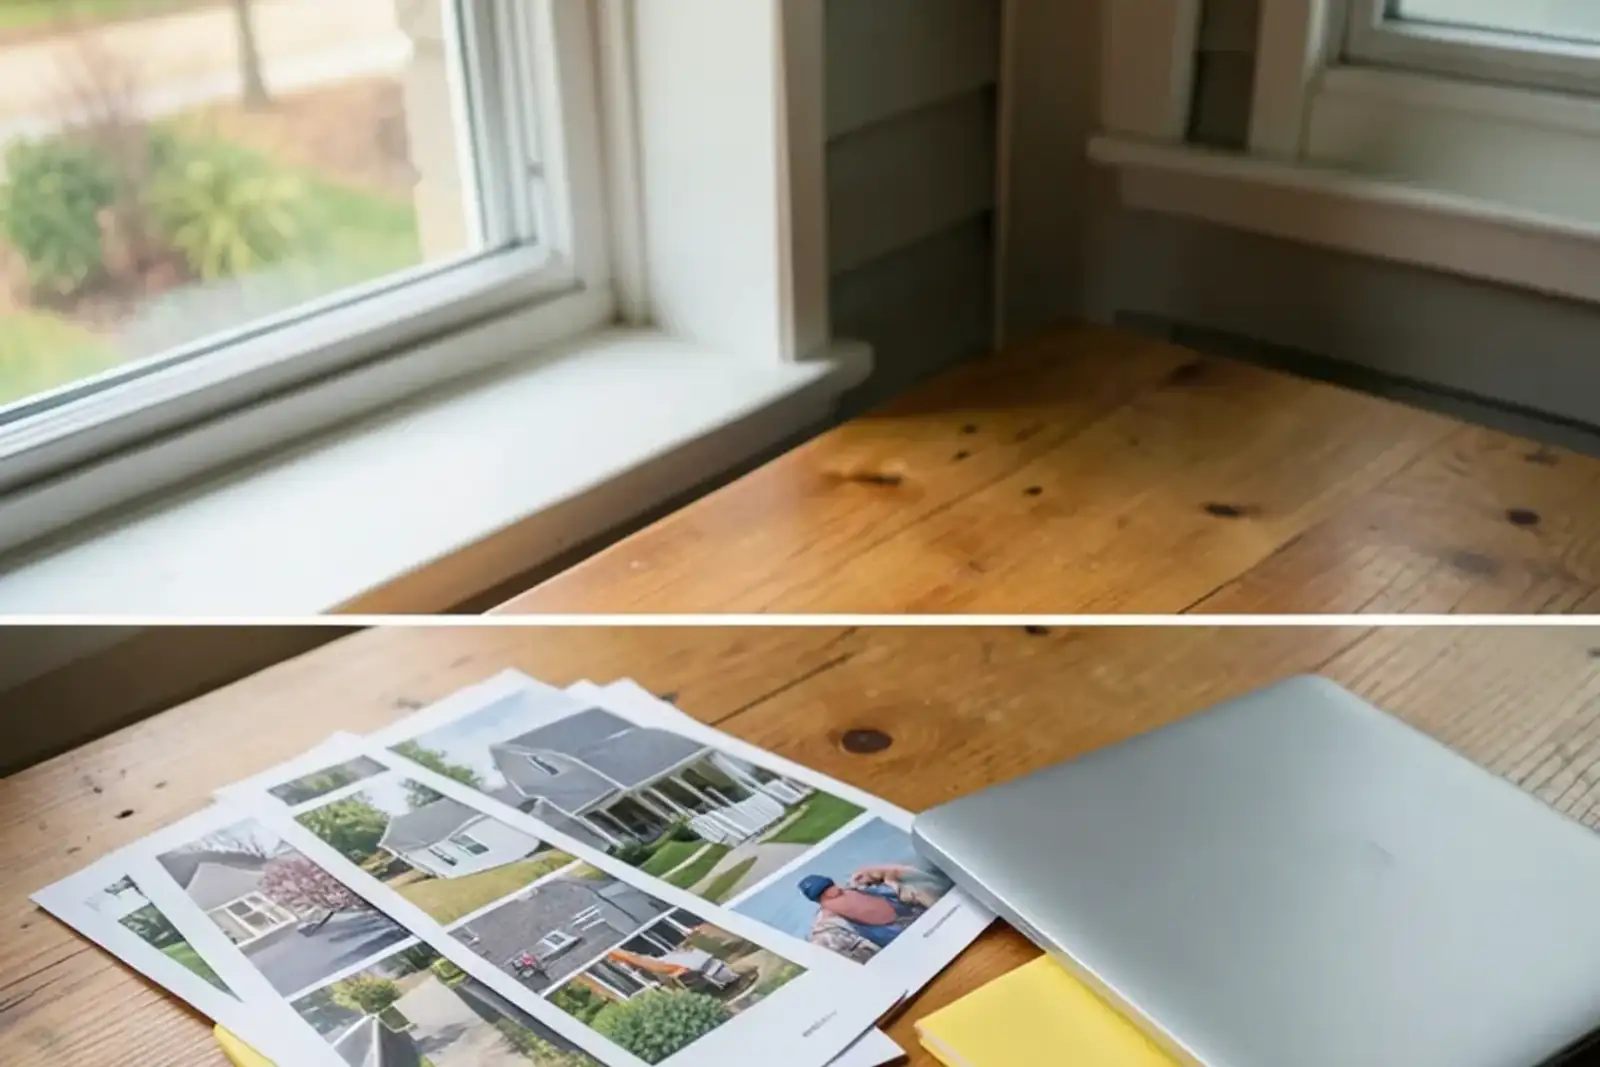
What an installer can add to a claim file
From our crew, a useful price for an insurance conversation separates three things: what the storm broke, what was already worn and what is extra. Ours are written after a visit, with gutter sections, hangers, downspouts and fascia work as separate lines.
A written price is more useful when it describes the condition of the metal as well as the work. If a run is creased, bent or torn, say so. If seams are dry and cracked, say that too. An honest note on what is old stops the file from claiming more than the storm did, and it protects you if the adjuster looks closely.
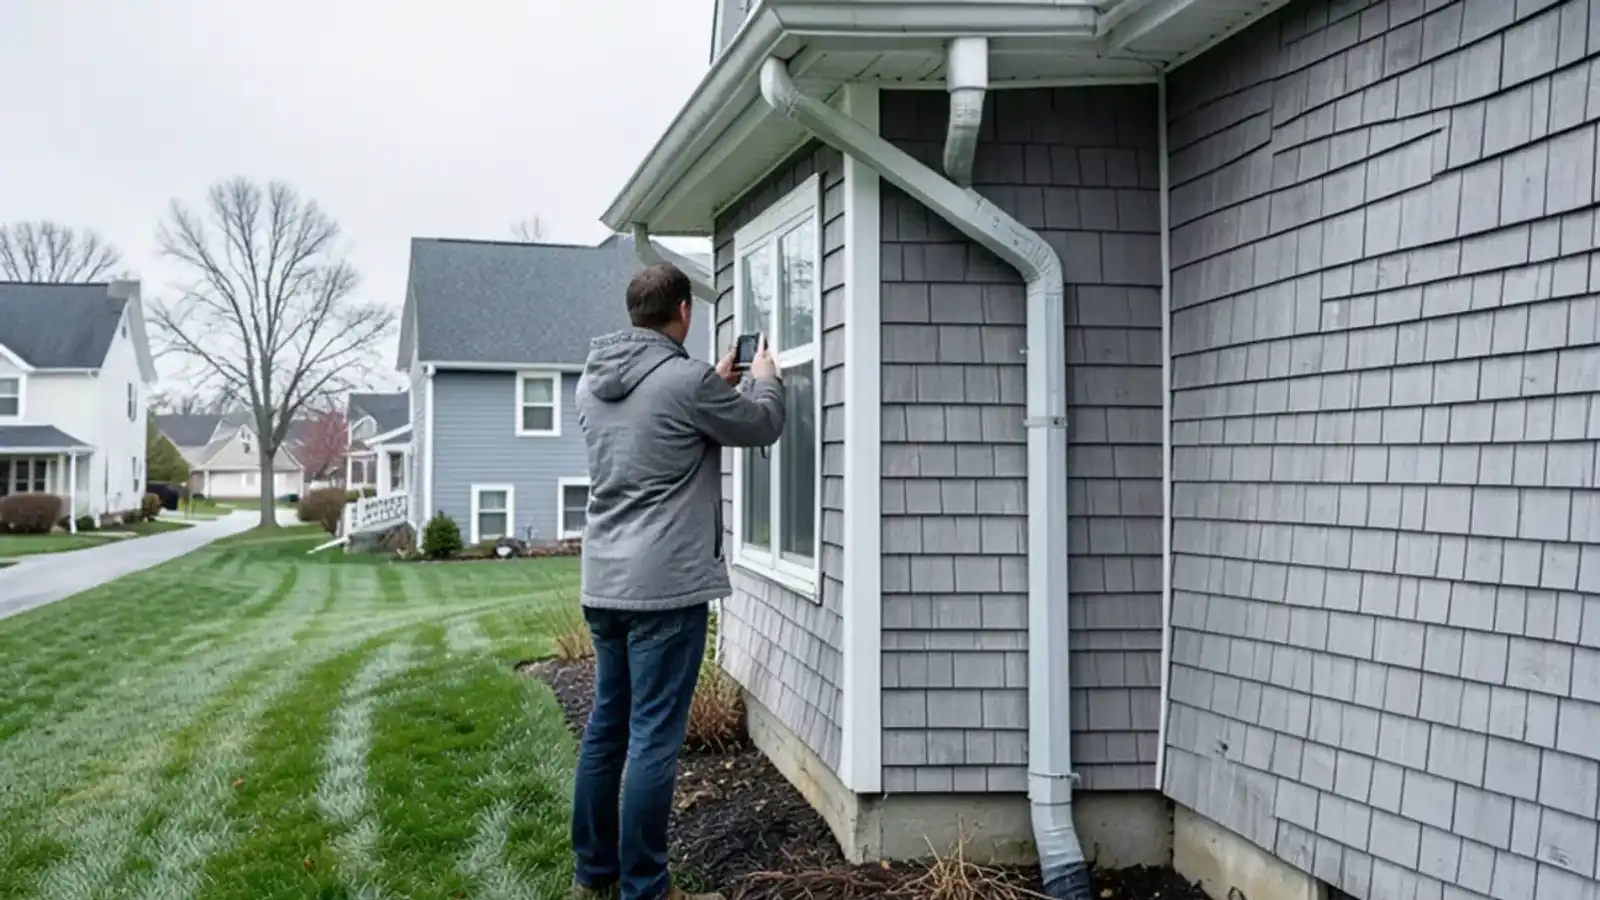
We cannot decide coverage, and a price from us does not guarantee a payout. We also do not file or negotiate claims for you. We can show what we see on the roof edge and describe what a repair involves. Our checklist for storm damaged gutters shows what to photograph while it is fresh.
Five situations, and what tends to matter in each
These are general illustrations. None of them says what your policy will do.
| Situation | What tends to matter | What to ask |
|---|---|---|
| A limb drops on one section | The cause is sudden and easy to photograph | Whether the section's cost clears the deductible |
| A windstorm lifts a run that was already soft and rusty | Whether the wind or the wear did the damage | How age and condition are weighed |
| Ice bows a run between hangers | Whether the load was sudden or built up over weeks | How snow and ice are handled in the policy |
| A whole side comes down with fascia and soffit | The total is larger and more is damaged | Which parts are dwelling coverage |
| Ice dam leak stains a ceiling | Gutter, roof and interior are three possible lines | What is covered for the damage that gets inside |
An adjuster usually works from the photos, the age and condition of the gutter and the written price, so those are the three things to have in order.
Questions to put to your agent
Call before you decide anything, and write the answers down:
- Are gutters covered under the dwelling part of my policy?
- Which causes of loss are covered, and which are excluded?
- What is my deductible for wind, and is it different for other causes?
- Do I need to report damage in a set time?
- Should I hold off on permanent repairs until an adjuster looks?
Keep your own records of upkeep too. Receipts for cleaning and repair show that the gutters were maintained, which helps separate sudden damage from neglect.
Ice dams and water inside the house
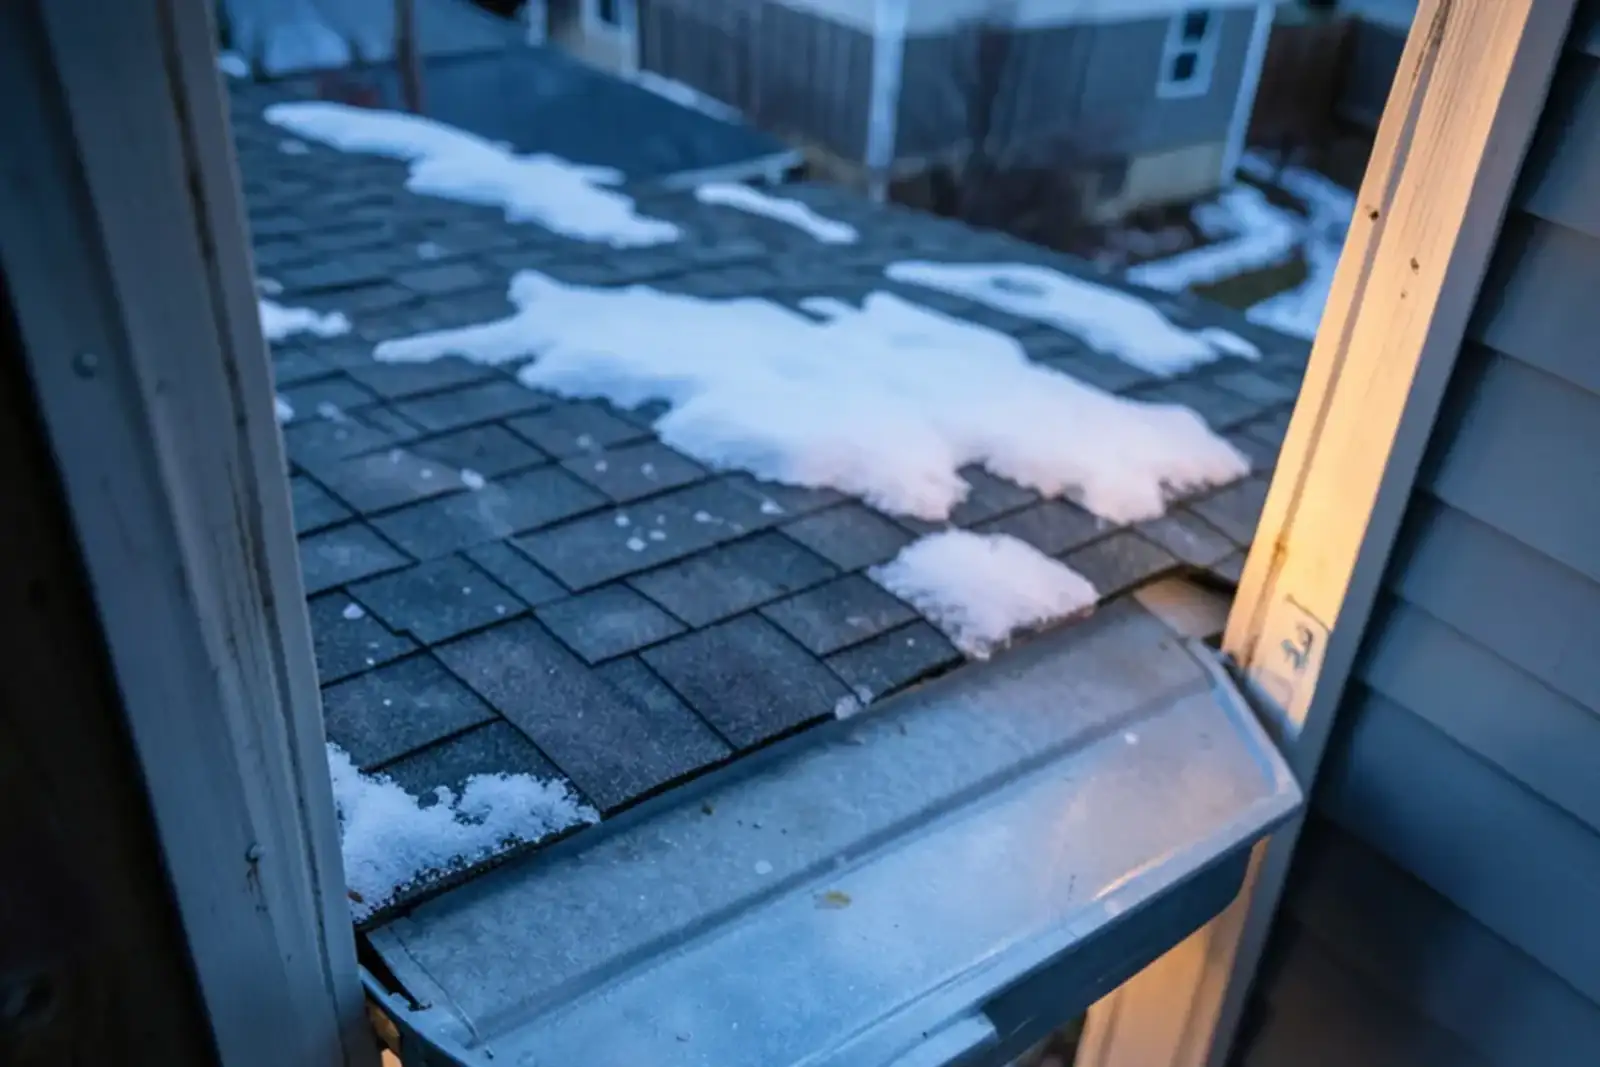
Ice dams are a mixed case. Gutter damage from the ice itself, and water that gets inside, may be handled differently under a policy. Insurers often ask whether the cause was sudden, and attic insulation and ventilation can come into the conversation. Ask your agent before assuming either way.
Each cubic foot of packed ice weighs between 57 and 60 pounds, so a gutter full of it can bow or pull away, as in the run below.
Some insurer guides say that paying to remove an ice dam is often excluded while the water damage it causes may be covered, though policies differ. That is a good question to ask your agent early, since it affects whether to hire removal before or after you report the loss. Our ice dam removal page explains what we can and cannot do about the ice itself. The real fix for ice dams is attic insulation and ventilation, and that is a maintenance matter, not a claim.
Damage photos and estimates near Exeter
We cover Exeter, about 25 minutes from our Hampstead base by our estimate. Exeter's median home was built in 1979, and the town has a historic core around the Squamscott River, so the age of a gutter is worth knowing before any claim. See our Exeter gutter service page for more.
Keeping the claim simple
Start with the policy and one phone call. Photograph first, make the house safe, ask your agent what they require and keep every receipt. If you have a dispute or a question your insurer cannot answer, the New Hampshire Insurance Department takes consumer questions about insurers. The policy and the insurer decide what is covered, and neither a gutter crew nor a blog post can.
When you are ready for a written price that lists the work line by line, call us at (208) 464-4195.
Quick answers
Does homeowners insurance cover gutters damaged by ice or snow?
It can, since many policies treat the weight of ice and snow as a covered cause, but the details vary. Insurers may look at whether the damage was sudden or built up over time. Read your policy, ask your agent and photograph the damage first. Your insurer decides, and the gutter's age and upkeep can matter.
Should I wait for the adjuster before repairing a fallen gutter?
Make the house safe first, and take photos before moving anything. Ask your insurer what temporary steps it expects and keep receipts. A gutter hanging over a door should not wait. For the permanent repair, a written price from the installer gives the adjuster something concrete, but the insurer decides what it pays.
Does insurance cover a gutter that failed from age?
Usually not. Insurers generally treat rust, old sealant, rot and general aging as wear and tear, which is a maintenance matter. If a sudden event such as a storm finished off an already worn gutter, the picture can get mixed. Your policy and your insurer decide, so ask before assuming.
Will an insurer pay to replace every gutter on an Exeter house if only one side was damaged?
It depends on the policy, and the insurer decides. Some pay to repair or replace the damaged part, and some consider whether the new section will match the rest. Ask your agent how matching is handled before you agree to a scope, and get a written price for both the damaged side and the whole run so you can compare.
Does homeowners insurance pay for gutter cleaning or guards on an Exeter house?
No, usually not. Cleaning and guards are maintenance and upgrades, not repairs after a covered loss. A claim for storm damage may pay to put back what was there, which is a different matter from adding something new. Keep receipts for cleaning, because a maintained gutter is easier to defend in a claim.
Sources
- Insurer and consumer-finance guides on gutter, wind, snow and ice coverage, read for general patterns only (web search, November 2026)
- American Community Survey 2020-24, Exeter NH median year built
Questions about your gutters?
25 Glenwood North Rd #16, Hampstead, NH 03841
(208) 464-4195
Mon–Sat 8am–6pm · Sunday closed